Market overview — definition, scope, and industry significance of Energy Behavioral Analytics Market
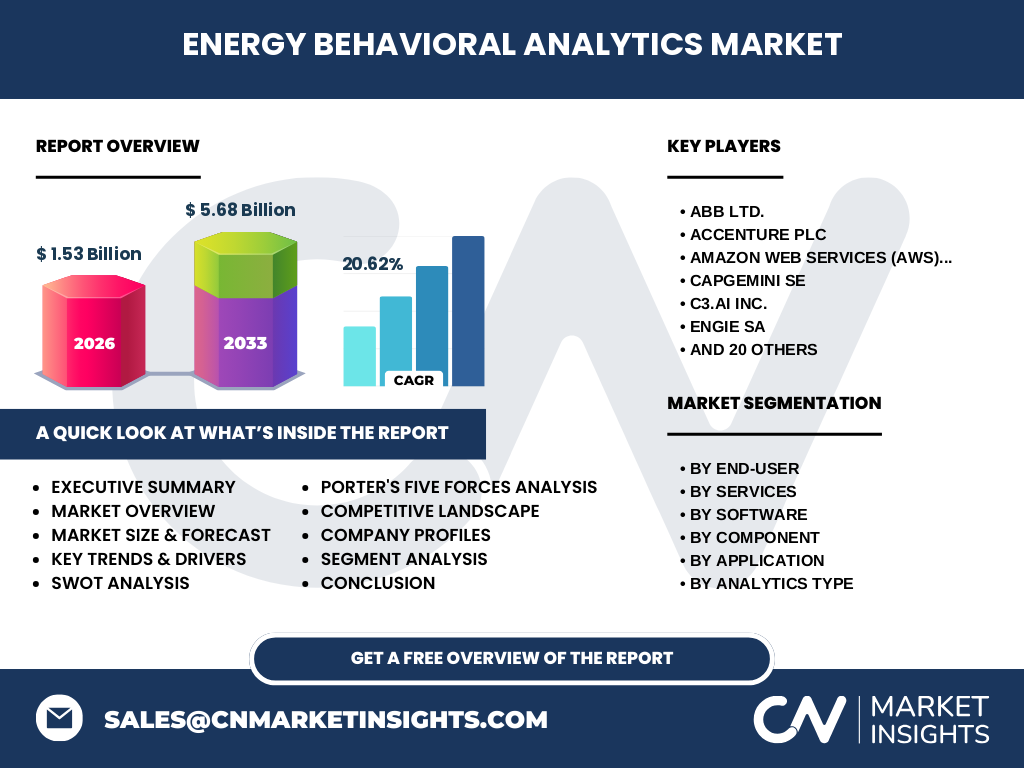
The Energy Behavioral Analytics Market represents a pivotal segment valued at $1.53 Billion in 2026. Our analysis indicates this market bridges advanced data science and consumer psychology to drive energy efficiency. Operating under strict regulatory frameworks by bodies like the Federal Energy Regulatory Commission (FERC), the sector focuses on processing granular smart meter streams to optimize load curves and curb peak demand across global power grids.
Key market drivers, restraints, challenges, and opportunities shaping Energy Behavioral Analytics Market
Structural growth stems from aggressive decarbonization mandates and the proliferation of advanced metering infrastructure. However, data privacy regulations such as GDPR act as localized restraints, challenging enterprise deployment velocity. Despite these hurdles, our research highlights massive opportunities for behavioral analytics platforms to integrate with distributed energy resource management systems, helping utilities navigate complex grid modernization challenges.
Emerging trends and growth patterns in Energy Behavioral Analytics Market
The shift toward real-time consumer engagement models is transforming how energy providers utilize behavioral insights. Predictive analytics and machine learning algorithms are replacing legacy reporting, allowing platforms developed by innovators like C3.ai and Uplight to deliver hyper-personalized energy-saving recommendations directly to residential and commercial end-users, fundamentally altering demand-side management.
COVID-19 impact analysis — how the pandemic affected Energy Behavioral Analytics Market and the recovery trajectory
Pandemic-induced lockdowns severely disrupted commercial load profiles and delayed critical smart grid rollouts. Yet, the crisis accelerated cloud-based software adoption as remote operations became mandatory. Our evaluation shows the post-pandemic recovery trajectory has been robust, driven by municipal and enterprise investments in resilient energy monitoring software to manage volatile consumption patterns.
Competitive landscape — major players, market concentration, and strategic dynamics
Market concentration is characterized by a mix of agile software pure-plays and diversified industrial giants. Industry leaders like Schneider Electric, Oracle, and Landis+Gyr dominate through end-to-end software ecosystems. Meanwhile, specialized disruptors leverage cloud architecture to carve out niches in demand response management, forcing established players into strategic acquisitions to maintain market share.
Executive summary — high-level synthesis of key findings about Energy Behavioral Analytics Market
The Energy Behavioral Analytics Market is poised for explosive expansion, scaling from $1.53 Billion in 2026 to $5.68 Billion by 2033 at a CAGR of 20.62%. This growth is heavily underpinned by the convergence of cloud deployment modes and advanced analytics types, compelling energy providers and enterprises to prioritize behavioral platforms for regulatory compliance and carbon reduction goals.
Market forecast — projected growth from 2027 to 2033
The data suggests exceptional momentum, projecting the market to surge from its 2026 baseline to reach $5.68 Billion by 2033, expanding at a compound annual growth rate of 20.62%. This trajectory is fueled by mandatory grid decarbonization targets and escalating enterprise demand for automated building energy management systems and prescriptive analytics solutions.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Segmentation spans across end-users, services, software, components, applications, analytics types, and deployment modes. The software category encompasses behavioral analytics platforms, demand response, and predictive tools, while services range from consulting to energy audits. Cloud deployment currently drives agility across residential and commercial applications, outperforming traditional on-premises models.
Regional market analysis — geographic distribution and performance across regions
North America leads consumption due to extensive smart grid mandates and early utility adoption. Europe follows closely, anchored by stringent European Union energy efficiency directives. Meanwhile, the Asia-Pacific region demonstrates the fastest relative growth, driven by rapid urbanization and massive infrastructure investments in smart metering across developing economies.
In-depth regional review — detailed examination of key regional markets
In North America, federal funding and state-level renewable portfolio standards accelerate software integration. In Europe, strict carbon reporting laws compel industrial enterprises to adopt advanced visualization and reporting software. Conversely, emerging markets in Asia-Pacific face localized grid constraints, prioritizing managed services and foundational energy monitoring software over complex cloud deployments.
Company profiles — strategic positioning of leading companies in Energy Behavioral Analytics Market
Key ecosystem participants include ABB, Siemens, Schneider Electric, Oracle, and specialized platforms like Uplight and GridX. Industrial giants leverage global scale and hardware integration, whereas software-centric innovators focus on modular analytics platforms, enabling seamless API integration with existing enterprise resource planning and utility billing architectures.
Porter's Five Forces analysis — competitive forces assessment
Rivalry is intense among software vendors, though mitigated by high switching costs associated with enterprise-grade platforms. Supplier power remains moderate due to open-source data analytics frameworks, while buyer power is high among major municipal utilities demanding bespoke customization. Threat of substitution is low given the specialized regulatory compliance embedded in modern energy behavioral tools.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths lie in robust predictive algorithms and proven energy savings. Weaknesses include high initial implementation hurdles for legacy utilities. Opportunities abound in expanding cloud-based building energy management systems for commercial real estate. Threats involve escalating cybersecurity vulnerabilities and shifting regulatory frameworks governing consumer data ownership.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw telemetry data from IoT sensors and smart meters. Data aggregators and cloud providers like Amazon Web Services process this influx, feeding specialized software developers who build behavioral analytics platforms. Value ultimately flows to utilities and enterprises, translating raw consumption metrics into actionable decarbonization strategies.
Investment insights — strategic recommendations and high-potential areas
Our analysis indicates investors should prioritize cloud-native software providers specializing in prescriptive analytics and demand response management. Companies offering integrated consulting and implementation services also present lucrative targets, as enterprises increasingly lack the internal data science expertise required to interpret complex energy audit findings.
Conclusion and key takeaways
The Energy Behavioral Analytics Market offers compelling growth, backed by a projected valuation of $5.68 Billion by 2033. Organizations that successfully merge cloud deployment with advanced behavioral platforms will capture disproportionate market value, helping stakeholders navigate complex regulatory mandates and surging enterprise demand for sustainable energy practices.
Research methodology — detail how baseline estimates are triangulated
Baseline estimates are meticulously triangulated by combining primary stakeholder interviews with C-level executives at major utilities, exhaustive trade registry data, and secondary macroeconomic indicators. Our quantitative models cross-reference historical smart meter deployment rates with regional regulatory filings to ensure precise market sizing for 2026 and accurate forecasting through 2033.
Scope of the report — coverage parameters and limitations
This report covers global revenue streams for energy behavioral analytics across all defined software, services, components, and deployment modes. Limitations include potential delays in official government statistical releases for emerging markets and the exclusion of unverified proprietary software deployments within private microgrids.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic activity highlights aggressive cloud partnerships and AI integration. Major players have launched enhanced predictive analytics suites designed to automate peak load shedding. Collaborations between technology vendors and regional power providers underscore a broader industry push toward scalable, API-driven behavioral platforms capable of managing decentralized renewable energy assets.